July 2026 inflation data delivered an uncomfortable reminder for technology investors: the cost of capital may not return quickly to the conditions that defined much of the 2010s.
The Federal Reserve’s preferred Personal Consumption Expenditures price index rose 3.7% year over year in July, while core PCE inflation was 3.3%, both still above the Fed’s 2% objective. The federal funds target range, meanwhile, remains 3.50% to 3.75% following the Federal Open Market Committee’s July 29 meeting.
The implications for technology are more complicated than the familiar idea that high interest rates are simply “bad for growth stocks.”
Large-cap technology companies, smaller publicly traded technology firms, and private technology businesses experience inflation and interest rates through fundamentally different financial mechanisms. Their exposure depends less on the word technology than on balance-sheet strength, cash generation, debt structure, pricing power, capital intensity, and how far future profitability sits from the present.
That distinction is becoming increasingly important as artificial intelligence pushes technology toward a more capital-intensive era.
In economics, interest rates act as gravity behaves in the physical world.
Buffett’s observation remains useful, but in today’s technology market gravity is not pulling equally on every company.
The Macro Backdrop: Inflation May Fall, but Cheap Money Is Not the Base Case
The Federal Reserve’s June 2026 Summary of Economic Projections illustrates the challenge.
Fed participants projected median PCE inflation of 3.6% for 2026, followed by 2.3% in 2027 and 2.0% in 2028. Their median projection for the federal funds rate was 3.8% at the end of 2026, 3.6% in 2027, and 3.4% in 2028.
But credible forecasters disagree materially on the inflation path.
The Congressional Budget Office earlier projected inflation of about 2.7% in 2026, with the federal funds rate averaging roughly 3.4% in the fourth quarter of 2026. The OECD has been more cautious, projecting U.S. headline inflation around 4.2% in 2026 in its March interim outlook and expecting policy rates to remain elevated.
That spread is itself informative.
Sophisticated investors may be better served by thinking in scenarios rather than asking for a single rate forecast. The technology market must increasingly operate in a world where a 3% to 4% policy rate could be normal for longer than many business models were originally designed to accommodate.
Large-Cap Tech: Higher Rates Hurt Valuations More Than Solvency
For the largest technology companies, interest rates primarily act through valuation and capital allocation, rather than financial survival.
Many mega-cap technology businesses generate substantial free cash flow, have strong credit profiles, and can access public debt markets on favorable terms.
Goldman Sachs Research has estimated that 72% of S&P 500 debt carries fixed rates extending beyond 2028, helping insulate large companies from immediate increases in borrowing costs. Its research also estimates that a 100-basis-point increase in real Treasury yields is associated with roughly a 7% change in the S&P 500 forward P/E multiple.
This produces an important distinction.
Higher rates may compress what investors are willing to pay for earnings without materially damaging the underlying company.
Large technology companies can even receive an offsetting benefit. Companies holding tens of billions of dollars in cash and marketable securities can earn substantially more interest income when short-term rates are elevated.
At the same time, the artificial intelligence investment cycle is changing this equation.
The Federal Reserve reported in July that investment-grade corporate bond issuance was particularly strong in early 2026, partly because large publicly traded technology companies increased debt financing for AI infrastructure expansion.
That matters because mega-cap technology is gradually becoming more capital intensive.
Data centers, semiconductors, electrical infrastructure, cooling systems and AI compute require physical investment on a scale that traditional software businesses did not.
The question for large-cap tech is therefore evolving from:
How sensitive is valuation to rates?
to:
Can returns on enormous AI capital expenditures remain comfortably above a structurally higher cost of capital?
That is a far more important long-term question.
Small-Cap Tech: Where Interest Rates Reach the Income Statement
Smaller public technology companies occupy a different financial world.
They generally have less cash, thinner margins, weaker negotiating power with lenders and less access to long-duration fixed-rate capital.
Federal Reserve research has repeatedly found that small businesses rely more heavily on bank financing than large corporations. Its July 2026 Monetary Policy Report described financing conditions for large businesses as generally accommodative while conditions for small businesses remained “somewhat restrictive,” with loan originations declining and business credit-card borrowing increasing.
This creates a more direct transmission mechanism:
Higher rates → higher interest expense → lower earnings and cash flow → reduced hiring and investment → slower growth.
For a profitable mega-cap company, a change in discount rates can alter its market multiple.
For a smaller technology business, the same monetary environment can alter its operating strategy.
The company may delay hiring engineers, reduce marketing, postpone acquisitions or issue equity at an unattractive valuation.
Inflation compounds the problem.
Technology companies are sometimes described as asset-light, but their major costs often include highly skilled labor, cloud computing, cybersecurity, software tools and increasingly AI inference and compute. A company without meaningful pricing power can therefore experience cost inflation before it can pass those increases to customers.
Scale becomes a form of inflation protection.
Private Tech: Interest Rates Create Financing Cliffs
Private technology is different again.
Public-market valuations adjust every trading day. Private-company valuations typically adjust when a financing, secondary transaction, acquisition or IPO forces price discovery.
This means higher interest rates can remain partially hidden inside private portfolios.
The economic value of a company may decline before its reported valuation does.
That creates what might be called a financing cliff.
A startup valued during a low-rate environment does not necessarily experience visible daily repricing. Instead, the adjustment may arrive suddenly when it needs another round of capital.
If growth has slowed, comparable-company multiples have fallen or investors demand higher returns, management may face a down round, structured financing, greater dilution or aggressive cost reductions.
Yet headline venture statistics can disguise this pressure.
According to the PitchBook-NVCA Venture Monitor, U.S. startups raised more than $400 billion during the first half of 2026, already surpassing the total for all of 2025. But the organizations emphasize that capital remains highly concentrated in artificial intelligence and large financings.
KPMG reported a similar pattern. U.S. venture investment reached $144.9 billion across 3,644 deals in Q2 2026, with much of the capital concentrated in AI and mega-rounds. Globally, the ten largest venture deals accounted for approximately $105 billion of Q2 investment.
That concentration changes how the statistics should be interpreted.
A booming AI fundraising market does not necessarily mean capital conditions have normalized for the median private technology company.
There may effectively be two private technology capital markets: one for businesses viewed as strategically important AI platforms or infrastructure, and another for nearly everyone else.
Inflation Creates Winners Inside Technology, Not Just Losers
Inflation also deserves more nuanced treatment.
Higher inflation can hurt technology through wage pressure, energy costs, cloud expenses and higher discount rates.
But nominal inflation can also raise revenues for businesses with contractual pricing escalators or strong pricing power.
The dividing question is not simply whether inflation is high.
It is:
Can revenue reprice faster than the cost base?
A dominant enterprise software platform with embedded workflows may raise prices with limited customer attrition.
A smaller SaaS provider selling a discretionary tool may instead encounter procurement scrutiny precisely when its own costs are rising.
PwC estimates that software-sector valuations remain roughly 30% below their peak, while investors increasingly distinguish between defensible platforms and more replaceable software products as AI alters competitive dynamics.
Inflation and AI disruption may therefore reinforce each other by rewarding companies with genuine pricing power while exposing businesses whose growth depended primarily on abundant capital.
The Overlooked Feedback Loop: AI Could Help Keep Capital Expensive
One of the more interesting long-term possibilities is that technology itself may influence the interest-rate environment confronting technology investors.
Artificial intelligence is often discussed as a potential disinflationary force because productivity improvements can lower the cost of producing goods and services.
But there is another side.
If AI meaningfully raises productivity and the expected return on investment, businesses may demand more capital to build data centers, semiconductor capacity, electrical generation and digital infrastructure.
The CBO explicitly notes that generative AI could contribute to interest rates remaining above pre-pandemic averages because productivity improvements increase the returns available on capital investment.
That leads to a counterintuitive possibility:
AI may eventually reduce some forms of inflation while simultaneously supporting a higher equilibrium cost of capital.
If that occurs, the technology winners of the next decade may not simply be companies capable of growing quickly.
They may be companies capable of producing unusually high returns on invested capital while funding growth without perpetual dependence on cheap external financing.
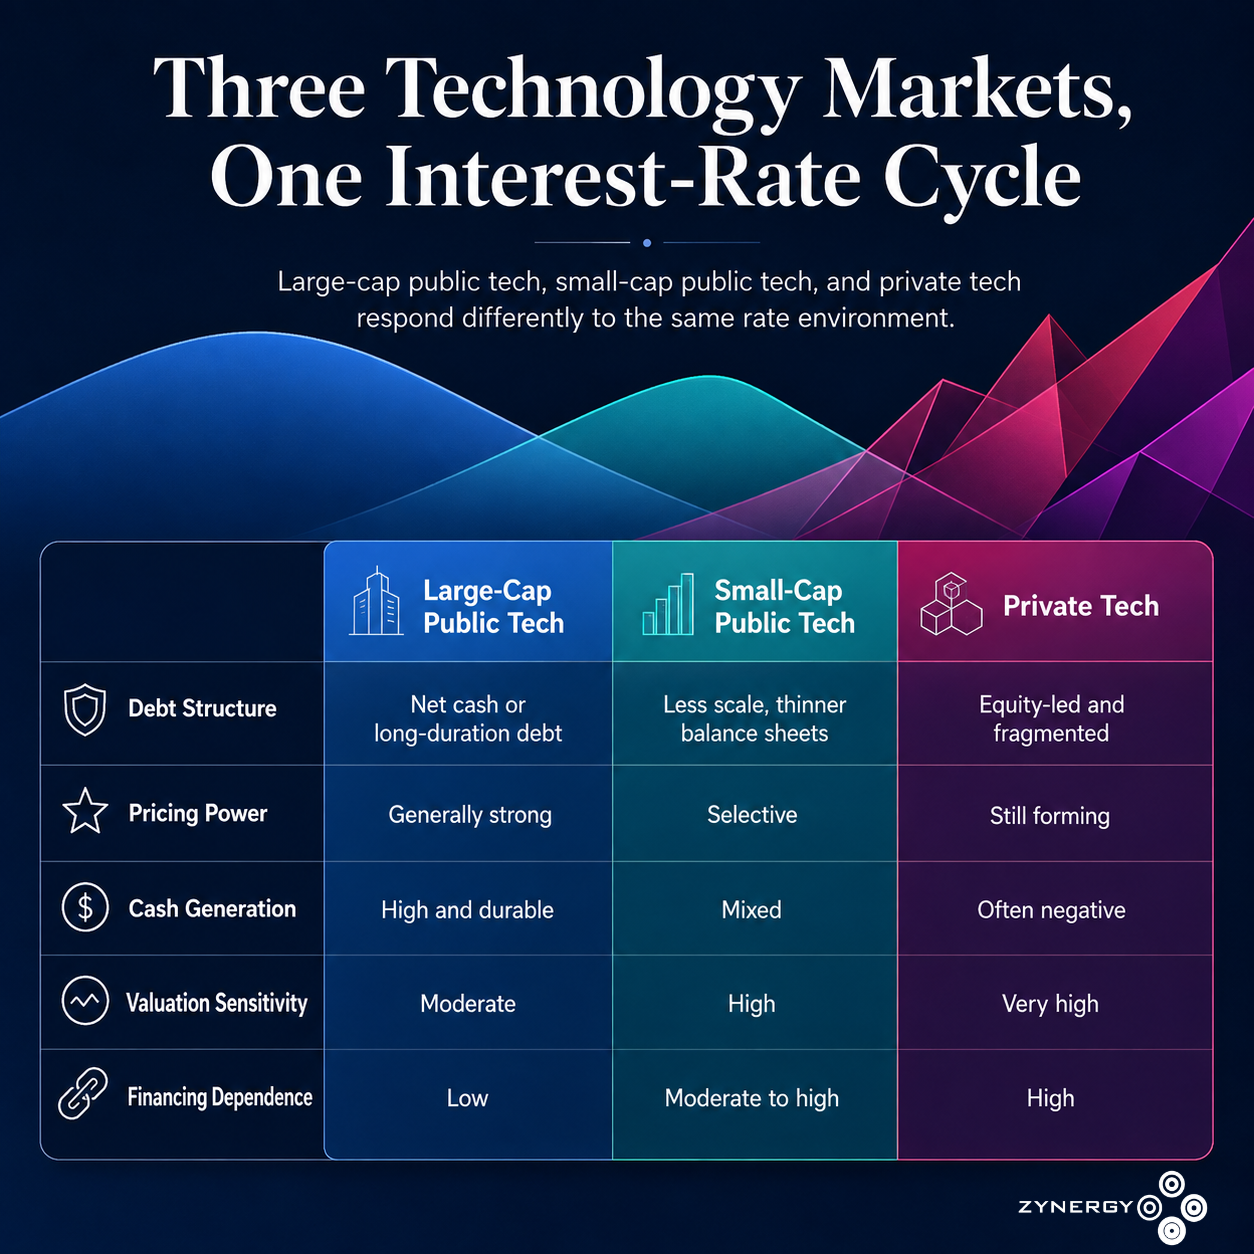
The difference is critical.
Large companies primarily face discount-rate risk.
Smaller public companies face financing and operating risk.
Private companies face liquidity and price-discovery risk.
Those risks can occur simultaneously even within the same technology subsector.
The next phase of technology investing may be defined less by who grows fastest and more by who can compound innovation efficiently when capital has a real cost. Interest rates are forcing investors to distinguish between technological ambition and financially durable innovation.
What To Watch
Rather than attempting to predict every Federal Reserve decision, executives, allocators and family offices may find several underlying indicators more useful:
- Interest coverage and debt maturity schedules, particularly among smaller public companies.
- Free cash flow relative to capital expenditure among AI infrastructure leaders.
- Revenue growth versus operating-cost inflation, a practical measure of pricing power.
- Private-company burn rates and time to next financing, especially outside the largest AI companies.
- Venture deal concentration, not simply aggregate fundraising dollars.
- IPO and secondary-market activity, which can reveal private-market valuations that quarterly marks cannot.
- Returns on AI capital expenditure, which may ultimately matter more than the absolute size of AI spending.
The Bigger Investment Question
The era of near-zero interest rates allowed investors to place extraordinary value on distant cash flows.
Today’s environment is imposing a different discipline.
Inflation remains above target. The Fed is maintaining a restrictive policy stance. AI investment is accelerating. Private capital is abundant in selected areas but increasingly concentrated.
The result is not necessarily a weaker technology sector.
It may instead be a more discriminating technology market.
Large-cap balance sheets, small-cap financing structures and private-company runway now matter alongside product innovation and revenue growth.
For investors accustomed to evaluating technology primarily through addressable markets and growth rates, that may be the most consequential change of all.
The central question is no longer simply:
How large could this company become?
It is increasingly:
What does it cost to finance the journey, and who captures the economics when capital is no longer free?
Zynergy Insights
Join the conversation with Zynergy Insights, where innovation meets disciplined investing. Follow our research and commentary on artificial intelligence, private markets, technology and the evolving architecture of global capital.
